I’ve always been cursed with being a go-to-guy.
People come to me with questions about tech or finance, and much like The Godfather himself I lean back in my chair and ponder whether they deserve my friendship.
Navigating questions around finance from the average person has been quite an eye opening experience for me.
Most people view the world of finance as other than themselves. Many take pleasure in knowing nothing about how the market works, even though a little knowledge can go a long way over the course of a lifetime.
Last week my girlfriend’s mother wanted to chat with me about investing. She had a good chunk saved in the bank and was exploring options. She booked a consultation with her bank (as is custom for the boomer) to present their options, which we went through together.
We congregated at the kitchen bench to discuss, much like I had done many times at 3am kick-ons.
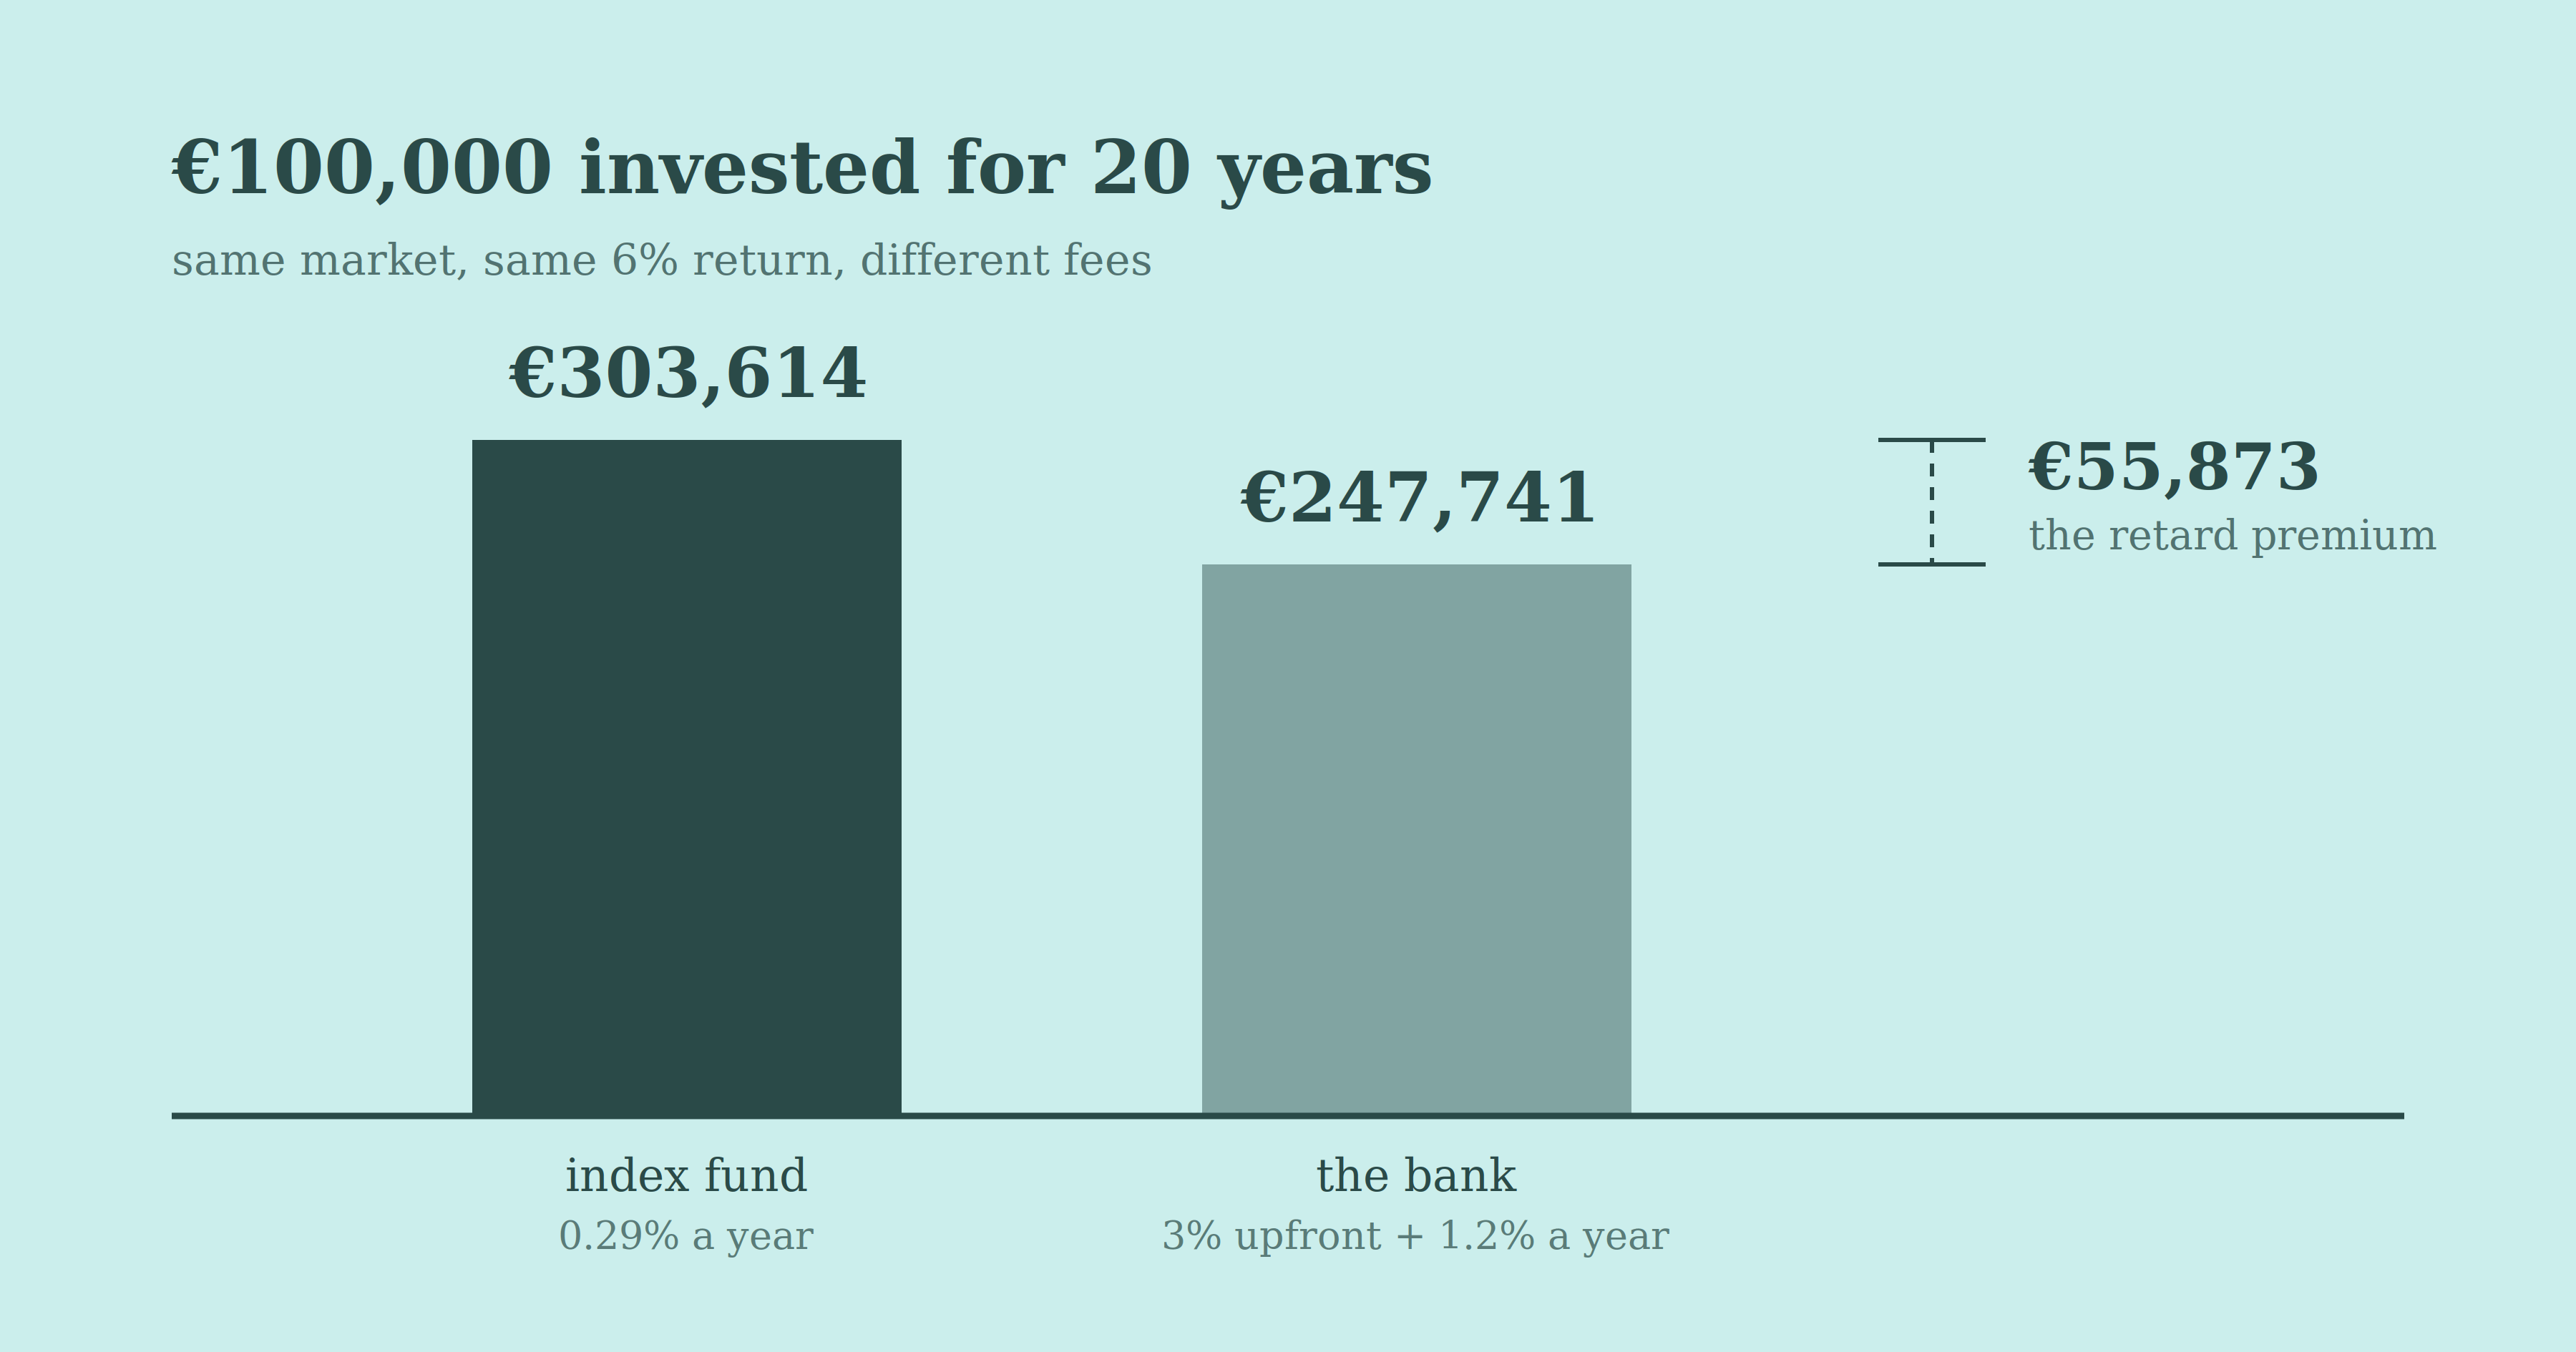
She opened the folder from the bank suggesting three different options. One was bonds at a standard market rate, but with their fee of 0.6%. Option two was a 2.5% deposit fee + 1.2% annual management fee, and option three was higher risk, 3% on deposit and the same management fee.
As someone who is financially literate, I was pretty disgusted to see these as the options presented. It shouldn’t be legal for banks to charge a deposit fee on an investment account. I’ve been managing my own money since I was about 15, but I’ve always bought and sold directly through order books.
The thought of investing at all time highs with the hope of 5-7% annual returns and having 4% of it go straight to the bank made me sick.
Then you consider inflation at 3% + 1.2% management fees (per year) and taxes at 30% of profits and you have a scenario where you’re extremely likely to be further behind than when you started, even as someone who seemingly did the right thing.
And all this is assuming the market goes up. We are at all time highs right now, if the market tumbles 10% then all of a sudden you’re paying 4% to lose 10%, how fun.
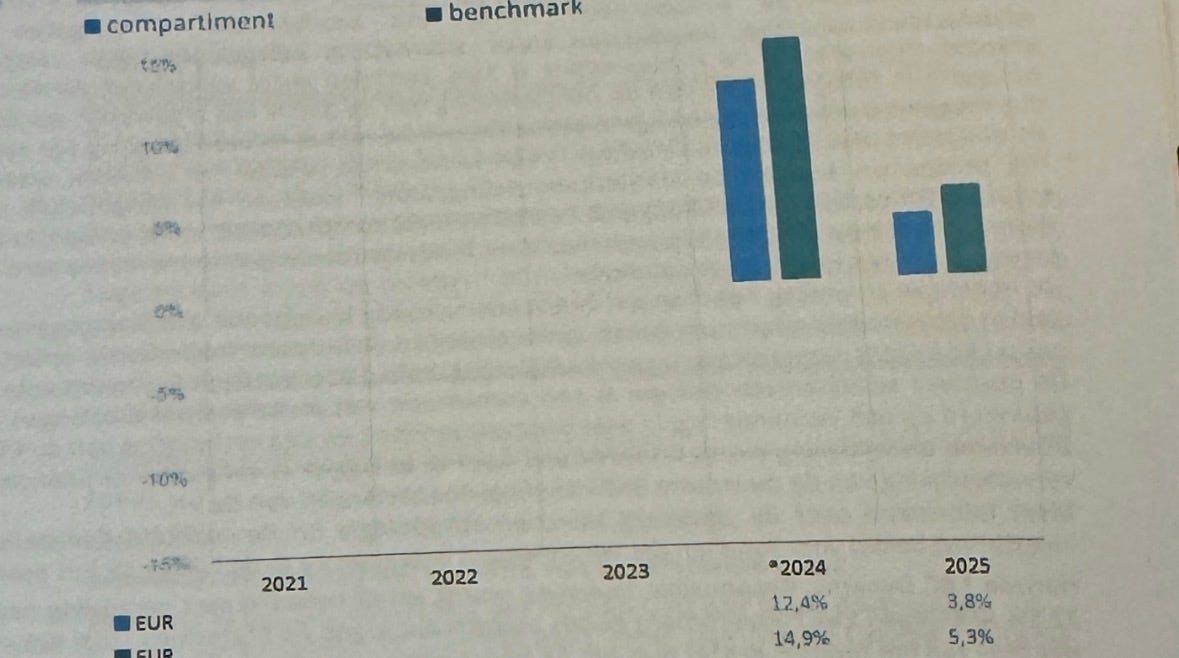
I pause briefly to say a little prayer for how much capital gets burnt paying fees to middle men who don’t need to exist. In the bank’s own reports they had also shown they had performed below their own benchmarks for the past decade. Which is something I could see on the page, but was certainly not easy to spot for someone new to the game.
This was someone going to where they were meant to go in order to get the knowledge they didn’t have. But it was kind of like going to the government and asking them to file your taxes for you. Like telling the mechanic you have a big budget and no idea about cars (turns out your everything is fucked mate).
Although I have spent a lot of time around managing money and trading, I had spent very little time around more conservative investing until quite recently.
I was much more of a gambling man than a serious person, and I suppose the same is still true today, but I’m trending in the right direction.
Last year I took it upon myself to build a more responsible portfolio, one that considered where I was in life and focussed on removing the need to work.
I have spent a lot of time on this Substack warning of the troubles with AI, so perhaps it is deserving that I finally give it some flowers. AI is a fantastic tool for learning something you don’t currently understand. It is also a wonderful tool to trick you into thinking you learned, when you were just told.
So the real focus should be on learning to learn in this new paradigm. Fighting our own hubris that tells us we are geniuses and know of something when we are unable to explain it ourselves.
If you buy a token through Coinbase you might pay a 5% fee. If you do the exact same transaction but know enough to click on ‘advanced trade’ and ‘market buy’ then you pay next to nothing. This is essentially how the entire financial system works.
You pay a retard premium.
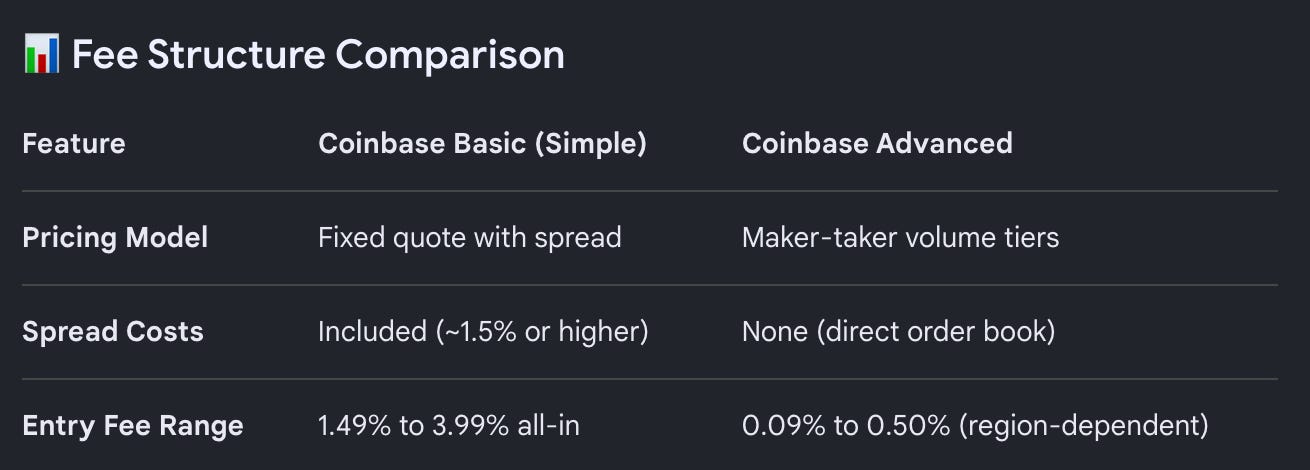
It’s the same as the bank charging 3% p.a. for extremely basic portfolio management that underperforms the benchmark. The 3% is your allocated retard tax for being too unaware, overwhelmed, or lazy to figure out the better ways to approach it.
My dream for AI is that it spawns the race to zero of this retard premium. That people can now verify if something is bullshit based on universal knowledge. That you might not be an expert but you can at least get from 0-1 and know how hard or expensive a certain thing should be.
A lawyer recently tried to suggest that something would cost significantly more than I thought was reasonable. I was right, and after a well-timed pushback her ChatGPT written email backed down into reasonable territory. A few years ago with the same situation I would have paid an ignorance tax and never known about it.
I’ve argued that AI has a gravitational pull towards a mediocre centre, and while I strongly believe that this is a dark future for creativity, it’s the perfect future for fairness.
There is no longer an edge in ripping people off, and we are more equipped than ever before to tell people to fuck off.
My girlfriend is making a cookbook and instead of hiring someone from Fiverr to design the template, I spent a few hours with Claude and came up with everything she dreamed of creating.
If I wanted it refined, I would have been able to provide a very-near-finished template to a designer to finalise, rather than paying their hourly rate from scratch.
There is no longer a reason to pay the retard premium for most people on the planet, and I really believe this leads to a more productive future. A more informed public has to be a good thing. People can be held accountable for when they misconstrue reality.
What we need to learn is how to first teach ourselves, through AI, to understand a certain topic.
I built my equities portfolio working closely with Claude, I then built a custom dashboard to track all of my wealth. I knew very little about retirement planning or tax optimisation with equities, and I certainly knew nothing about code.
What I did know is that I could continue to ask questions and use my common sense to pick the path forward. That I could have things explained to me in exactly the way I needed them explained, then re-explained, until I was spoon fed enough knowledge to be able to explain it myself.
Pretty much everything is now a solved problem, and knowing how to access the solution becomes a legitimate differentiator. Most of the time you can probably get 60-70% of the way there. There has never been a better time to be insatiably curious.
Sam Altman in an interview recently said that “becoming high agency” and “getting good at generating ideas” are more important than learning to code right now.

Although I think Altman is mostly a heaping pile of compost, I agree with him here. Becoming high agency with the self-belief that you can conquer almost any new quest is the edge of the future.
Next week I am meeting with my girlfriend’s mum to advise her how I think she should invest her money. It will likely go into the same index funds that the bank would have put her money into, or the ones that they had underperformed.
The only fee that she will be exposed to is the 0.29% that is automatically taken from the funds price each year. This would have likely also been true with her investments if she put it through the bank, but they would never have told her about that fee. When we know nothing we are exposed to everything.
I am a generous middle man, so I am to be compensated in a nice home cooked meal. There is opportunity that exists to turn high agency into real compensation. You can essentially arbitrage your knowledge of the access to knowledge, which makes you valuable.
Odd jobs used to be created in the form of mowing the lawn or transferring data to a new phone, now the surface area for what you can help others with has increased 100 fold. People everywhere are paying the retard premium on everything they have, all their bills and services are exposed.
There are many win-win situations that exist where you help others and get paid for doing so. This is the beginning of the end for taxing the ignorant.
My dad always (painfully) questioned experts. He still to this day continues to say to never trust anyone that calls themselves an expert. I’ve disagreed with him for most of my life because I found that mindset generally unhelpful, but perhaps he was not wrong, he was just early.
Now is the age to question experts, to tell the bank to take their 3% deposit fee and go fuck themselves. Since the dawn of man we have been grifted, cheated and lied to. Although I expect all of those to continue, we are now empowered to say miss me with that bullshit.
I am never paying the retard tax again.